Where Should I Put My 401(k) Money After Retiring in Eatontown?
Your 401(k) does not have to move the day you stop working, and sometimes it should not move at all.
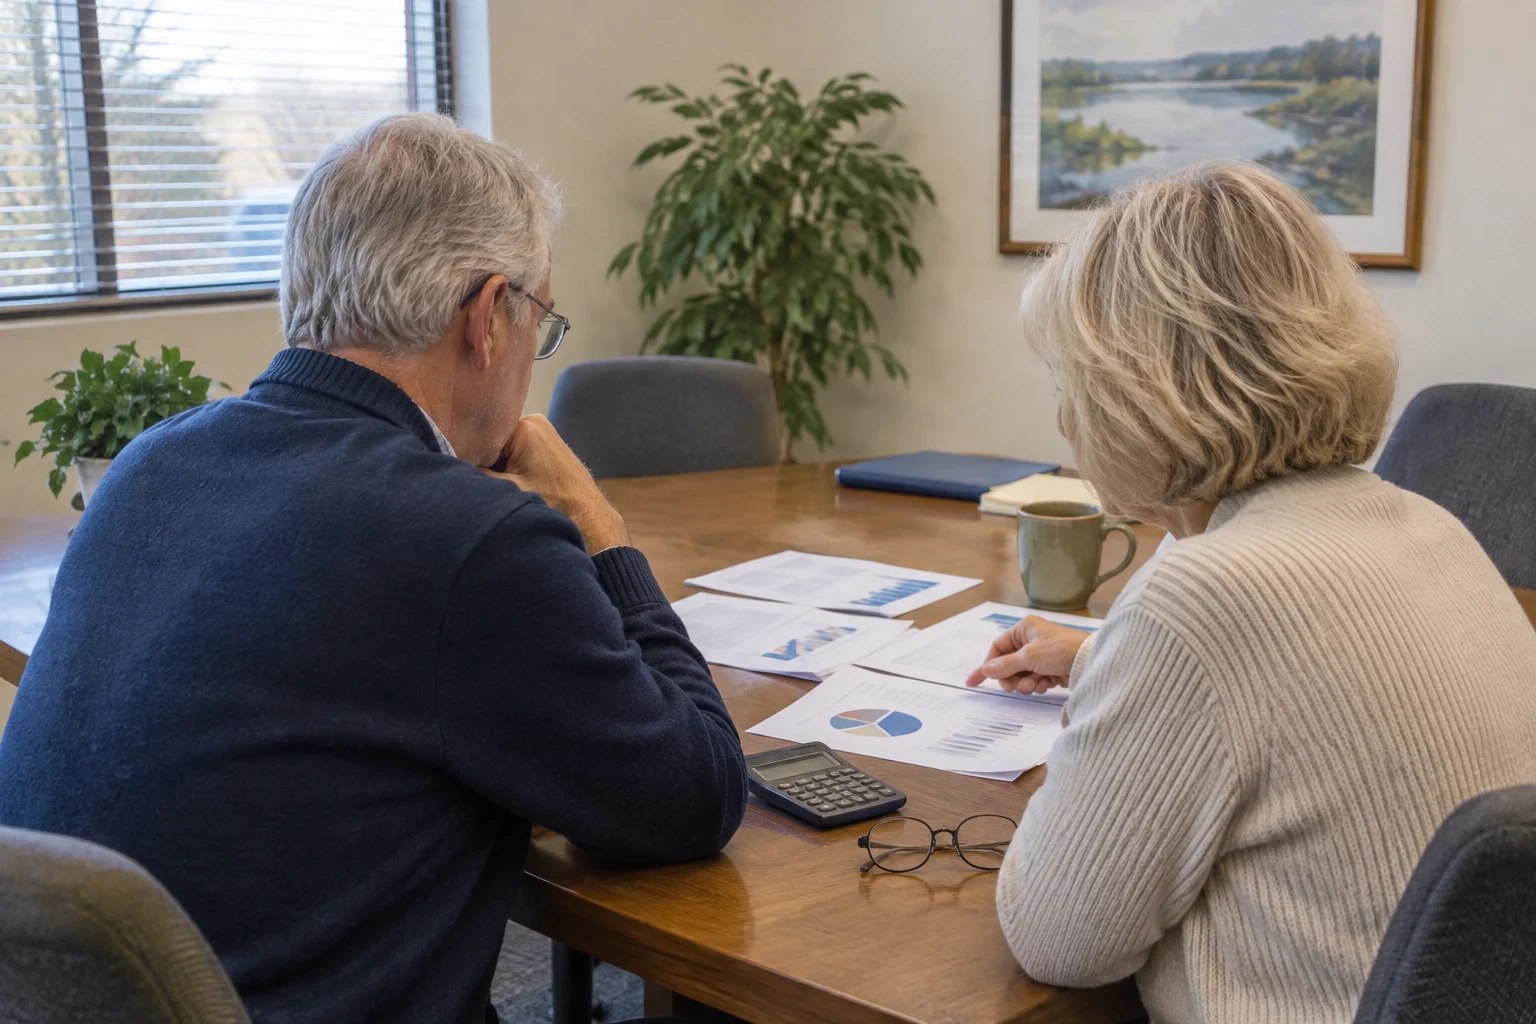
Where to put 401k money after retirement?
Often the best place for your 401(k) money after retirement is right where it is, as long as the plan has low fees and decent fund choices. When it does not, a direct rollover to an IRA usually makes sense. The right answer depends on your age, your fees, your taxes and when you need income.
What are your choices when you leave the job?
Most retirees have four basic options. You can leave the money in your old employer's plan. You can roll it into an IRA. If you take another job, you may be able to move it into the new employer's plan. Or you can cash some or all of it out.
Each one has a cost and a benefit. None of them is right for everyone. The mistake we see most is acting fast because a mailer or a phone call made it sound urgent. Your 401(k) is not going anywhere while you think it over.
- Leave it in the plan: simple, often low cost, fewer investment choices
- Roll to an IRA: more choices and more control, fees vary widely
- Move to a new employer plan: keeps things together if you keep working
- Cash out: full income tax on the amount, plus possible penalties if you are young enough
When does leaving it in the plan make sense?
Our habit is to look at what you already have before we suggest changing it. A lot of large employer plans offer index funds and institutional share classes with very low costs. You may not get those prices in a retail account. If your plan is one of them, staying put can be the smart, quiet choice.
Age matters too. If you left your job in or after the year you turned 55, many plans let you take withdrawals from that plan without the 10% early withdrawal penalty. Roll that money into an IRA and you usually lose that break until 59 and a half. For someone retiring early, that alone can be a reason to wait.
Employer plans also come with strong federal creditor protection. IRAs are protected too, but the rules work differently. If that matters for your situation, it is worth asking before you move anything.
- Low fund fees and a solid lineup of index funds
- You retired at 55 or later and may need money before 59 and a half
- You hold company stock that could qualify for special tax treatment
- You like having fewer accounts and fewer decisions
When is a rollover to an IRA the better move?
Sometimes the old plan just is not good. High fees, a short list of expensive funds or clunky rules on withdrawals can cost you real money over a 20 or 30 year retirement. That is when we explain plainly why a change makes more sense.
An IRA gives you a wider choice of investments and more control over how and when you take money out. It can also pull several old 401(k) accounts into one place. Fewer accounts means fewer statements, easier required distributions and a clearer picture of your whole portfolio.
How you move the money matters. Ask for a direct rollover, where the plan sends the funds straight to the new account. If the check comes to you instead, the plan must withhold 20% for taxes, and you have 60 days to deposit the full amount or the shortfall gets taxed as income.
- Your plan charges high fees or offers few good funds
- You have two or more old 401(k) accounts to combine
- The plan limits how often or how much you can withdraw
- You want room to do Roth conversions in low-income years
How do you turn the account into a paycheck?
Where the money sits is only half the question. The other half is how you draw it down. A common approach is to keep a year or two of spending in cash or short-term bonds, so a bad market does not force you to sell stocks at a low point.
Order matters for taxes. Many retirees spend from taxable savings first, then pre-tax accounts like a 401(k) or IRA, then Roth money last. That is a starting point, not a rule. In years when your income is low, such as before Social Security or required distributions begin, converting some pre-tax money to Roth can lower the tax bill later.
Required minimum distributions now start at 73 for most people retiring today, and at 75 for those born in 1960 or later. Plan for them early. A big forced withdrawal stacked on Social Security and a pension can push you into a higher bracket and raise Medicare premiums.
What does New Jersey tax mean for your 401(k)?
New Jersey generally taxes 401(k) and IRA withdrawals as income. It also has a retirement income exclusion that can shelter some of that money for residents who meet its age and income limits. Where you land on those limits can change how much you want to withdraw in a given year.
Because the federal and state rules interact, we look at both together. A withdrawal plan that looks fine on the federal side can cost more than it should once state tax is added. Our tax management work is built around catching that before the money moves.
More questions about your 401(k) in retirement
- Do I have to take money out of my 401(k) at a certain age?
- Yes. Required minimum distributions start in your 70s, and the exact starting age depends on the year you were born. If you are still working and do not own a large share of the company, that employer's plan may let you wait.
- What should I do with company stock in my 401(k)?
- Slow down before rolling it. There is a tax rule called net unrealized appreciation that can tax the growth on company stock at capital gains rates instead of income rates. Once the stock is rolled into an IRA, that option is gone.
- Can I split my 401(k) between staying put and rolling over?
- Many plans allow a partial rollover. Some people leave part of the money in the plan for its low-cost funds or early access and move the rest to an IRA for flexibility.
- Should I put my 401(k) into an annuity?
- Maybe a portion, if you want a steady check you cannot outlive. Read the fees, surrender periods and terms closely first, and do not move the whole account just because one product was pitched to you.
Talk through your 401(k) before you move it
Call and set up an introductory meeting at our office or by phone or video. Bring your plan statement and fee notice. We will look at what you have, tell you plainly if it is working, and explain when a change makes more sense.